
Venture capitalist Justine Moore clarifies a previous statement about AI and writing that she says was intentionally misinterpreted. She emphasizes that she does not believe AI will replace human writers, but she does expect that many writers will increasingly incorporate AI tools into their creative process. She draws an analogy to the range of tools and assistance authors already use today, such as word processors, suggesting AI is simply another addition to the writer's toolkit rather than a wholesale replacement for human creativity.
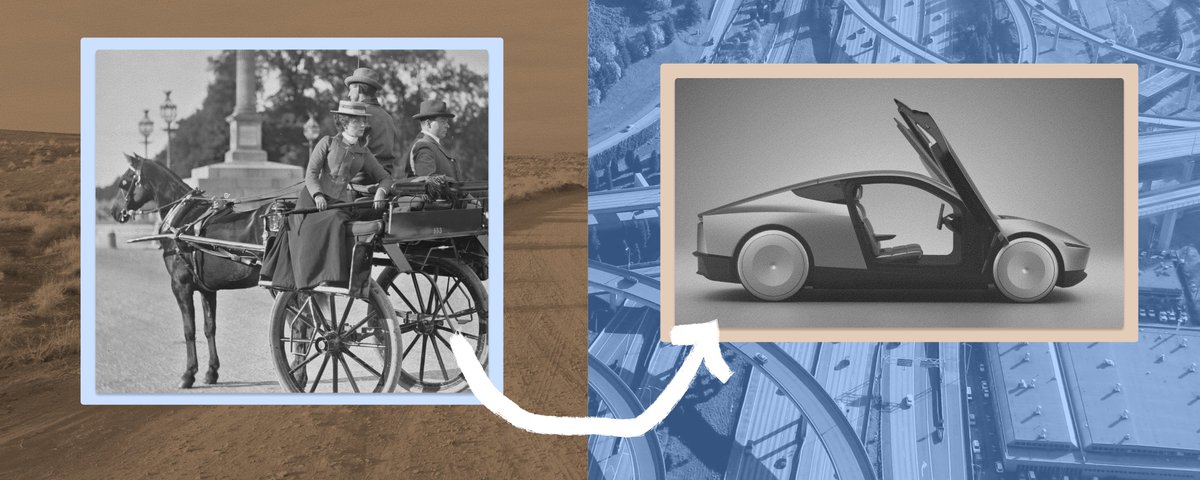
Joanne Chen of Foundation Capital presents findings from interviews with 25 companies about how AI is driving structural organizational change, not just individual productivity gains. The research reveals dramatic shifts: a 120-person engineering team planning to shrink to 25, expert-to-generalist ratios moving from 1:6 to a target of 1:100, and traditional roles like product, engineering, and design collapsing into fewer hybrid positions. The piece draws an analogy to factories switching from steam to electricity — the real gains came not from swapping power sources but from redesigning the entire system around the new technology.
The article identifies four human roles that remain essential in the AI-augmented org: chief accountability officers (executives who own outcomes), systems architects (who design human-agent collaboration), relationship experts (who maintain human-to-human trust), and validators (who review and approve agent outputs). Validator demand is expected to follow a bell curve, peaking in 2–4 years before declining as AI systems self-improve — but a critical "one-generation problem" emerges: if agents handle all junior work, the next generation of experts may never develop the foundational skills needed to validate AI output.
Chen maps four company archetypes along digital-vs-physical and product-vs-service axes, each facing distinct reorg patterns. Digital services firms face the most immediate pressure, as agents increasingly are the product. Seven startup opportunities emerge from these shifts, including tools for human system architects (like Arize), validator platforms (like Turing), agent-native infrastructure (like Sixtyfour), and AI-native services firms (like ConverzAI and Tessera Labs). The piece concludes that systems thinking — the ability to design workflows across humans and agents — is the most valuable and hardest-to-develop skill in the emerging organization.
Ann Miura-Ko, a well-known venture capitalist and co-founding partner at Floodgate, shares a link on X (formerly Twitter). The post from April 14, 2026 contains only a URL with no additional commentary or context, making it difficult to determine the specific topic or insight being shared without accessing the linked content directly.
Deedy introduces what he calls "Neolabs" — a term for pre-revenue, scale-stage startups focused on long-term AI breakthroughs rather than immediate commercialization. He compiles a comprehensive list of 50 such companies, positioning them as a distinct category in the AI startup ecosystem.
The post highlights a growing trend of ambitious AI ventures that prioritize fundamental research and breakthrough capabilities over near-term revenue, suggesting these Neolabs represent a significant and trackable segment of the artificial intelligence landscape. The accompanying image presumably details all 50 startups on the list.
This article from The VC Corner examines how AI-powered small teams are fundamentally reshaping the startup landscape, challenging the traditional assumption that scaling requires large workforces. It highlights remarkable examples like Midjourney reaching $200M ARR with just 10 people, Cursor hitting $100M ARR in 21 months with 20 employees, and BuiltWith generating $14M/year with a single employee. The piece references Sam Altman's prediction that one-person unicorns will emerge, noting that solo founders already account for 35% of the 2024 startup class according to Carta.
The article balances optimism with pragmatism, outlining significant challenges that lean teams still face: scalability limitations, employee burnout (72% of startup founders report mental health issues), skill gaps, and the threat of larger competitors who can replicate features or acquire smaller rivals. Certain industries like biotech, manufacturing, and cybersecurity remain inherently resistant to ultra-lean models. The piece advocates for a hybrid model that combines AI efficiency with strategic human expertise, citing McKinsey research showing companies blending AI with human decision-making are 20% more successful. Founders are advised to balance lean efficiency with sustainable growth, while investors should evaluate whether a startup's team structure realistically matches its scaling ambitions.
Chamath Palihapitiya highlights a new investment strategy being tested by major venture firms including Khosla Ventures, General Catalyst, and Thrive Capital. The approach involves acquiring mature, low-tech service businesses — such as call centers, accounting firms, and similar operations — and modernizing them internally using AI tools.
This signals a notable shift in venture capital strategy, moving beyond funding startups toward buying established businesses with stable revenue and applying AI to dramatically improve their efficiency and margins. The trend suggests that some of the biggest returns from AI may come not from building new products, but from transforming traditional service industries that have been slow to adopt modern technology.
Sam Altman announces that OpenAI has offered to invest $2 million in tokens into every startup in the current Y Combinator batch. He expresses excitement about the emerging trend of "tokenmaxxing" startups — companies that leverage large amounts of AI compute tokens both for their internal operations and the products they build. The post signals OpenAI's strategic move to embed itself deeply into the YC startup ecosystem by subsidizing AI usage at scale.
This is a notable development as it represents a shift in how AI companies support early-stage startups — not through traditional equity investment, but through compute credits as a form of capital. The concept of "tokenmaxxing" suggests a new class of startups whose core competitive advantage revolves around maximizing their use of AI inference and generation capabilities.
Ravi Mhatre of LSVP shares his six biggest takeaways from Davos, emphasizing that most enterprises are still thinking too small about AI. He sets the stage by noting that training compute has increased ~4x in the last 12 months while inference costs have dropped ~100x on average over the same period, underscoring the rapid pace of change in the AI landscape.
The post signals a growing gap between the pace of AI infrastructure advancement and enterprise adoption strategies, suggesting that companies need to be far more ambitious in their AI plans to keep up with the accelerating capabilities and declining costs in the space.
Paul Graham shares a contrarian insight about the current startup landscape: while AI represents the biggest opportunity for founders, the most underpriced opportunity lies in non-AI ideas. He argues that because the majority of founders are flocking to AI, good non-AI startup ideas are being systematically overlooked, creating an asymmetric advantage for those willing to pursue them. The implicit advice is that market attention creates blind spots, and founders with strong non-AI concepts should seize the moment precisely because competition for those ideas is unusually low.
Molly O'Shea highlights General Catalyst's AI Roll-Up strategy, noting that the firm screened 70 industries but exercised strict discipline by selecting only 10 for their approach. The post breaks down the compelling unit economics: even modest 20% revenue growth combined with a flat cost base and 20–30% task automation can transform a business running 10–15% EBITDA margins into one achieving roughly 30% margins, effectively doubling free cash flow. This illustrates how AI-driven operational efficiency, rather than top-line hypergrowth alone, can be the real value creation lever in roll-up strategies.